Help with roof insurance claims in Greer, done honestly and in full
Slopes torn up by wind, hail strikes, or a tree through the decking: we inspect the roof, record the damage, meet with the adjuster and write the estimate in the format carriers pay from. Your deductible is never something we bargain with.
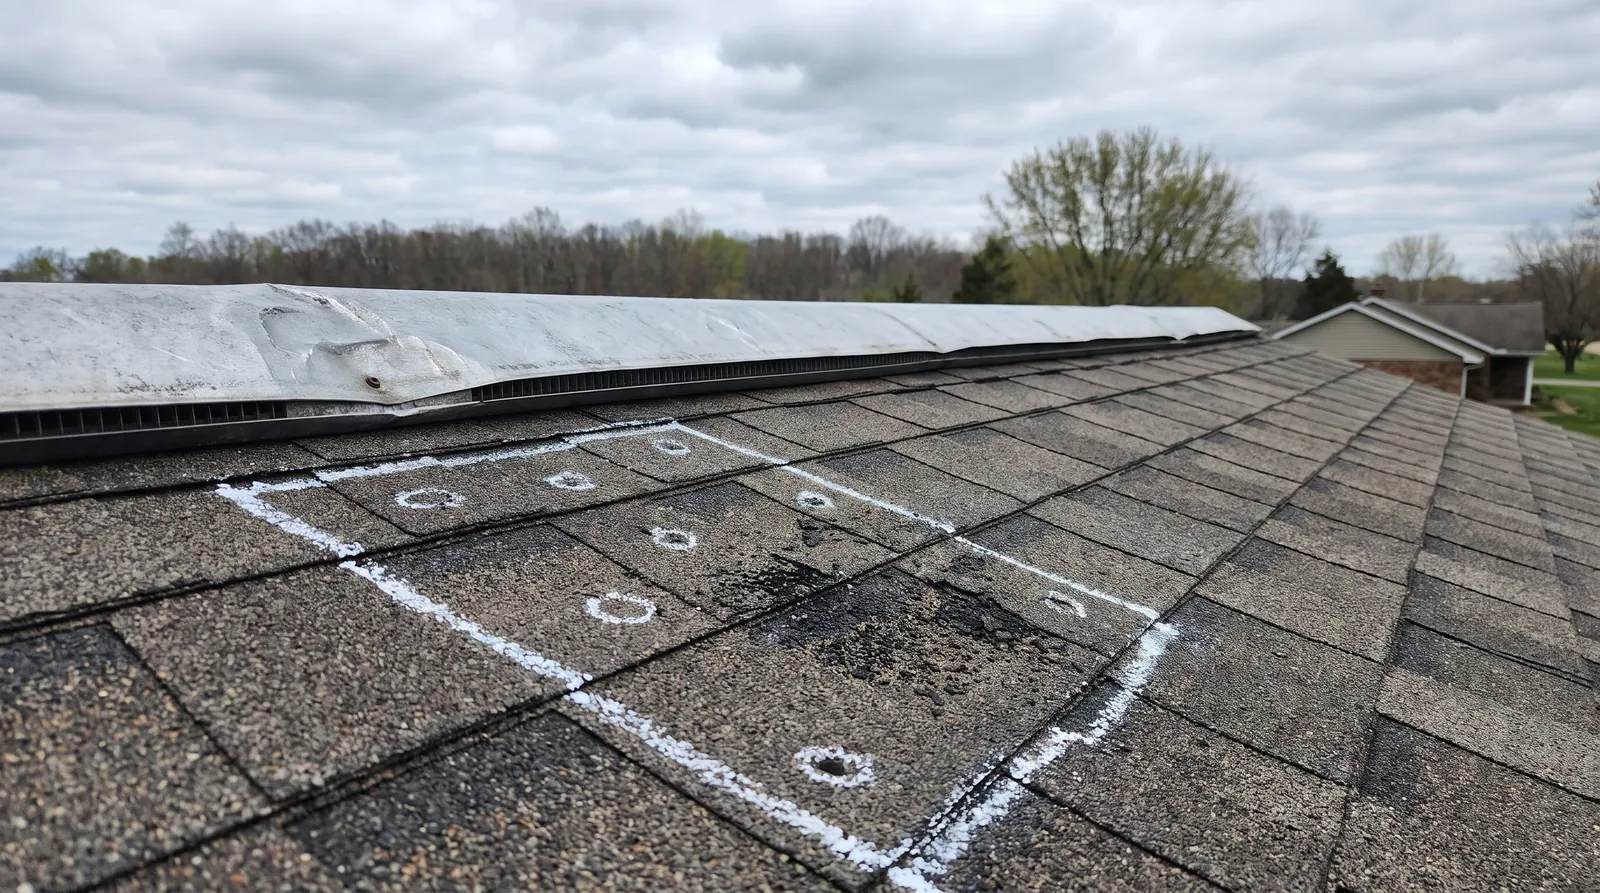
After a storm, insurance pays for most of the new roofs that go on in Greer. The way the claim is handled decides whether you end up with a whole new roof or a patched slope and an argument. Our first step is a free inspection that documents actual damage with actual photos, because not every roof has a claim. When yours does, we record the damage, help you file, stand on the roof with the adjuster so nothing gets skipped, and write an estimate that lines up with the Xactimate pricing carriers rely on. If the adjuster's scope leaves out items such as code requirements, the steep-slope charge or a second layer, we send a supplement backed by photos and code citations.
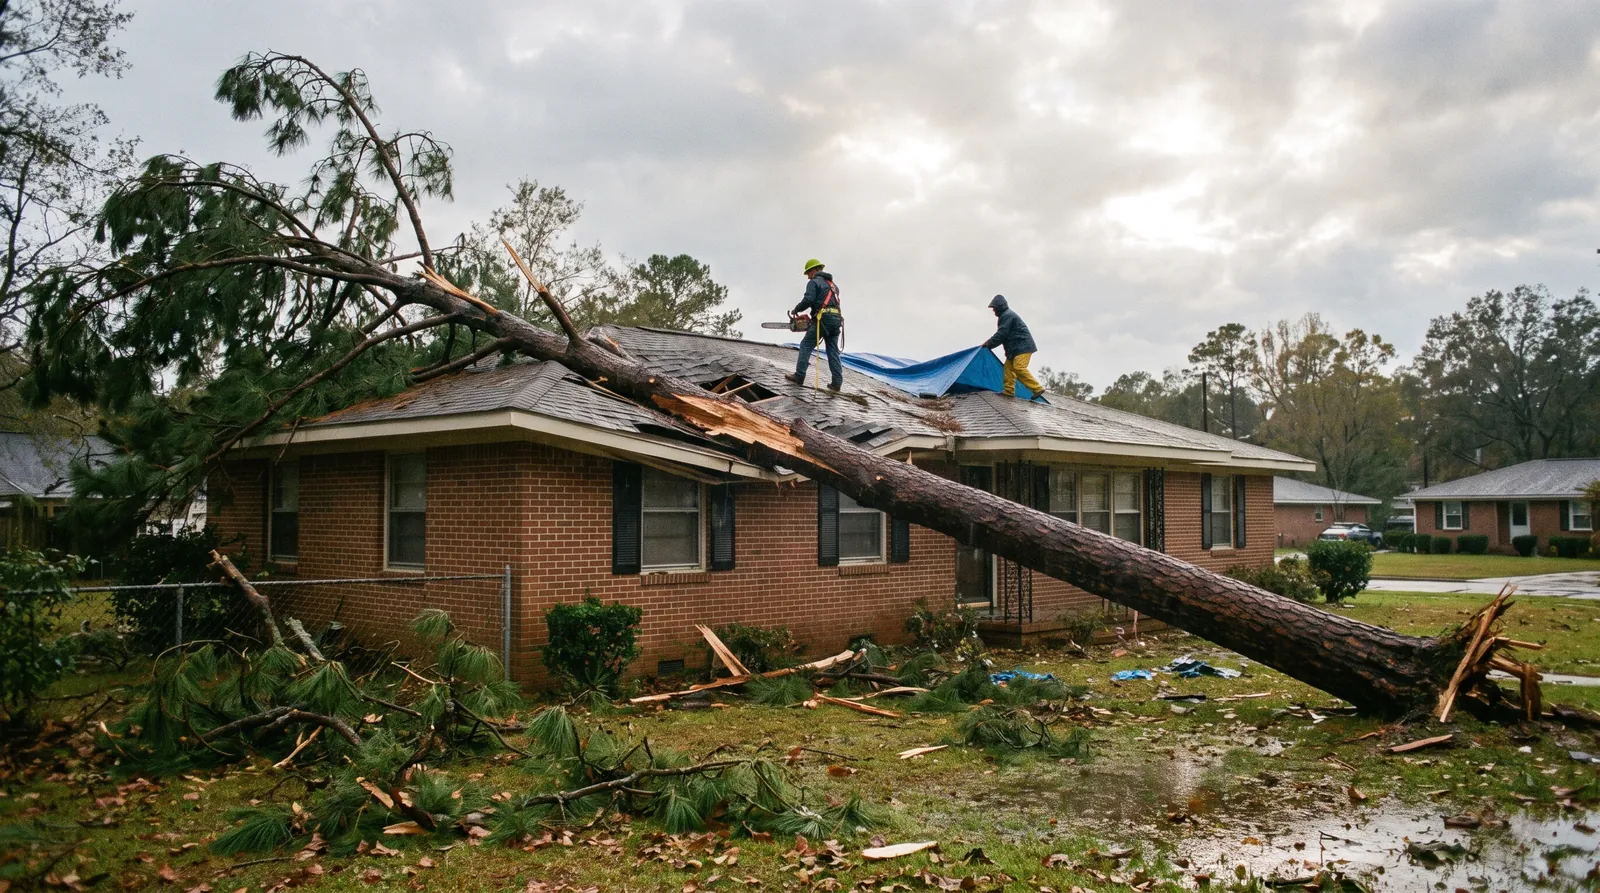
On deductibles, South Carolina law leaves no gray area. A contractor who offers to waive or absorb yours is committing insurance fraud, and a homeowner who agrees to it is too. We will not do it. What we will do is make sure the claim includes all it should, like ridge vent, ice-and-water, drip edge, decking and code upgrades, so the deductible is the only thing you pay. Between Hurricane Helene and the storms after it, people across this area have seen the difference between a roofer who handles a claim properly and a storm chaser.
The work, piece by piece
Storm inspection at no charge
Photos, documentation and an honest answer. If the damage is not enough for a claim, we tell you.
Help filing
Which part of the policy applies, how the wind/hail deductible works, and what to say and send.
On the roof with the adjuster
We walk it together so wind creases, hail bruises and collateral damage all get counted.
An estimate built like Xactimate
Line items in the same format and at the same pricing carriers use, which speeds up approval.
Supplements
Code items, decking, steep and high-roof charges and a second layer, all documented and sent in.
ACV, RCV and the holdback
We explain the held-back money and make sure the recoverable depreciation is paid once the work is done.
Your cost on a roof insurance claim in Greer, SC
| Item | Usual price, installed | Good to know |
|---|---|---|
| Storm inspection with documentation | Free | Photos plus written findings |
| Filing the claim and meeting the adjuster | Included | Part of every approved job |
| Partial claim, wind damage repaired | $1,200 – $6,000 | Shingles matched where we can |
| Full replacement on an approved claim | Your deductible | Usually 1–2% of dwelling coverage, or $1,000–$2,500 |
| Code items such as ridge vent, ice-and-water and drip edge | Often covered | Through Ordinance & Law coverage |
| Supplement for items left off | No charge | Sent in with photos |
When a replacement claim is approved, the deductible is what you pay out of pocket. The inspection, documentation, adjuster meeting and any supplements come with the job.
From the job photos
Insurance claims: what people ask us
Does filing a claim make my premium go up?
In South Carolina, weather claims are treated as no-fault and usually do not increase your own premium the way a liability claim would, although carriers do re-rate entire ZIP codes after major storms. A single storm claim seldom matters. Three within five years can.
How does a wind/hail deductible work?
Many South Carolina policies now include a separate wind/hail deductible of 1 to 2 percent of the dwelling coverage, which is $3,000 to $6,000 on a $300,000 house, in place of a flat $1,000. Look at your declarations page before you file, and we are glad to go through it with you.
Would you waive my deductible?
No. In South Carolina that is a crime for both of us, and a roofer who offers it is showing you how they run their business. We make sure the claim is complete so that the deductible is all you pay.
The adjuster only approved one slope. Is that final?
Not always. If your shingles have been discontinued and cannot be matched, or if damage shows up on more than one slope, we send a supplement with documentation. Plenty of one-slope approvals end up as full replacements.
What does recoverable depreciation mean?
The carrier first pays the depreciated amount, or ACV. It pays the holdback, which is the rest of the RCV, after the work is finished and invoiced. We send the completion paperwork so that money is released.
What is the deadline to file?
Your policy sets it. Many in South Carolina allow one year and some allow less. File as soon as you know about the damage, and get the inspection done beforehand so the claim is accurate.