Your deductible is likely a percentage
Policies written in South Carolina over the last few years usually carry a separate wind/hail deductible, set at 1 or 2 percent of the dwelling coverage. On a house insured for $350,000, that is $3,500 or $7,000, and it applies to every windstorm or hail claim. Some policies stack a named-storm deductible on top of that. The declarations page tells you which ones you carry.
Here is why it matters. With a 2 percent deductible, a repair claim for $6,000 pays you nothing at all. A $16,000 replacement claim pays $9,000.
How the money is paid out
Under replacement cost value coverage, the first check is the actual cash value. That is the full replacement cost minus depreciation for the age of the roof. The carrier keeps back the rest, called recoverable depreciation, and releases it after the job is finished and invoiced. A roof that is 15 years old could be depreciated by half, so the second half arrives once the work is done.
Policies with ACV-only roof coverage are different. You receive the depreciated amount and nothing after it, which can be as little as a third of what the roof costs to replace. South Carolina carriers are adding this by endorsement to more and more older roofs. Look through your policy now for an ACV endorsement or a "roof surface payment schedule", before a storm forces the question.
When the new shingles will not match
No South Carolina statute forces a carrier to replace undamaged slopes so that the roof matches. Even so, policy language and case law usually call for a "reasonably uniform appearance." If your shingle has been discontinued and the one damaged slope cannot be matched, you have a case for replacing the whole roof. That case needs proof: the discontinuation notice from the manufacturer and photos showing the mismatch. When the facts support it, we put that file together.
Waiving a deductible is a crime
Under South Carolina law, a contractor who rebates, waives or absorbs a deductible commits a crime, and so does the homeowner who takes the offer. A roofer who makes that offer is padding the claim to pay for it, and that is fraud as well. The legitimate way to protect yourself is a claim with nothing missing, including code items, decking, steep charges, gutters and the other things carriers tend to leave off the first scope. Then the deductible is your only cost.
Items the first estimate often leaves out
Adjusters build estimates in Xactimate from a checklist. On the first pass, these items are commonly missing:
- ridge vent and soffit intake that code requires
- ice-and-water shield and drip edge
- tearing off a second layer
- labor charges for steep pitches and two-story houses
- replacement decking
- gutters and downspouts
- reflashing skylights
- permit fees
A supplement that includes photos and the code references gets them added to the claim. Supplements are a routine part of the process and do not mean anyone is fighting.
Deadlines and your rights
Report damage quickly. Many policies give you one year from the date of loss, and some give less. South Carolina's unfair claims practices rules require carriers to acknowledge and act on a claim within set time limits, and the SC Department of Insurance accepts complaints when a claim stalls. The contractor is your choice, not the carrier's. You are also never required to sign something at the door, whether it is an assignment of benefits or a contingency contract, without reading it first.
Common questions
Will a single storm claim push my premium up?
Weather claims are rated on a different basis than liability claims, and one of them seldom changes your premium by itself. South Carolina carriers do raise rates across whole areas after bad storm years no matter what. Several claims within a few years can get a policy non-renewed.
My roof is 18 years old. Will the carrier replace it?
Yes, if covered storm damage is present. Do check for an ACV roof schedule, though. That endorsement limits payment on older roofs to the depreciated value.
The adjuster called it wear and tear. Now what?
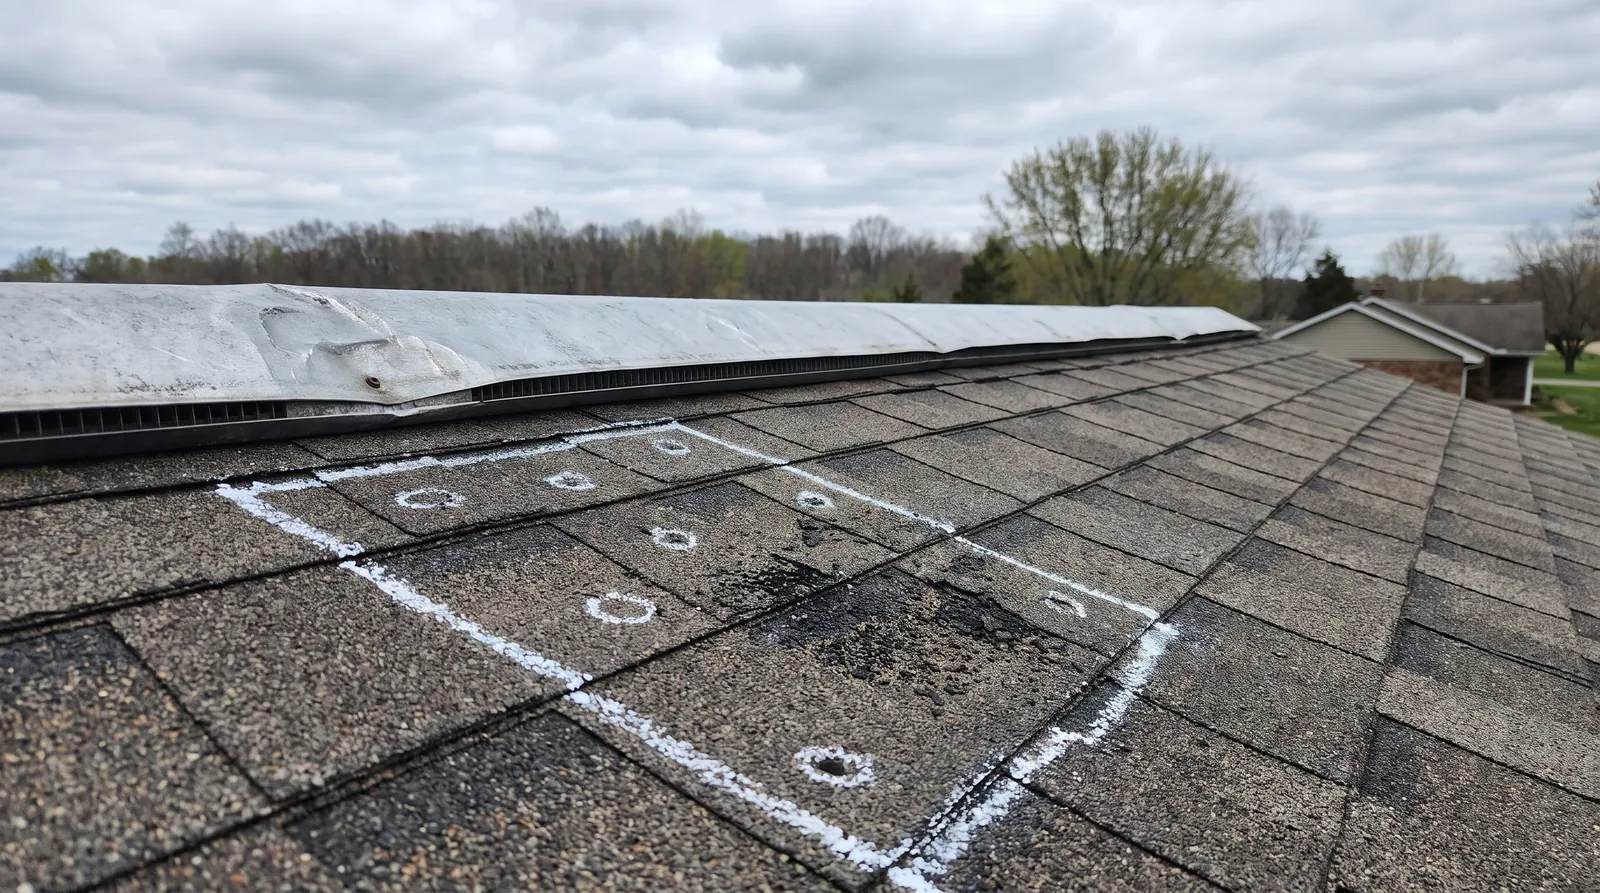
Wear is not covered, but adjusters also overlook hail bruising and wind creases. The next move is a second inspection with test squares and photos, followed by a request to re-inspect. We handle both.
Should I sign the contingency agreement a roofer handed me?
Read it first. A fair one says you will hire that roofer if the claim is approved, at the price insurance approves, and that you can cancel if it is denied. A bad one assigns your claim to them or binds you no matter what the price is.
Does the insurance company pay you directly?
No. The carrier pays you, along with your mortgage lender if you have one, and you pay us. We send the completion paperwork that gets the recoverable depreciation released.
Related: Claim help from us · Storm and tree damage · Roof inspections · Cost of a new roof